EV Data Privacy: How Your Vehicle's Information Shapes Insurance Premiums
The data collected by your electric vehicle holds immense value, extending beyond performance metrics to influence your insurance premiums. Understanding evolving data privacy laws is crucial for EV owners navigating this complex intersection.
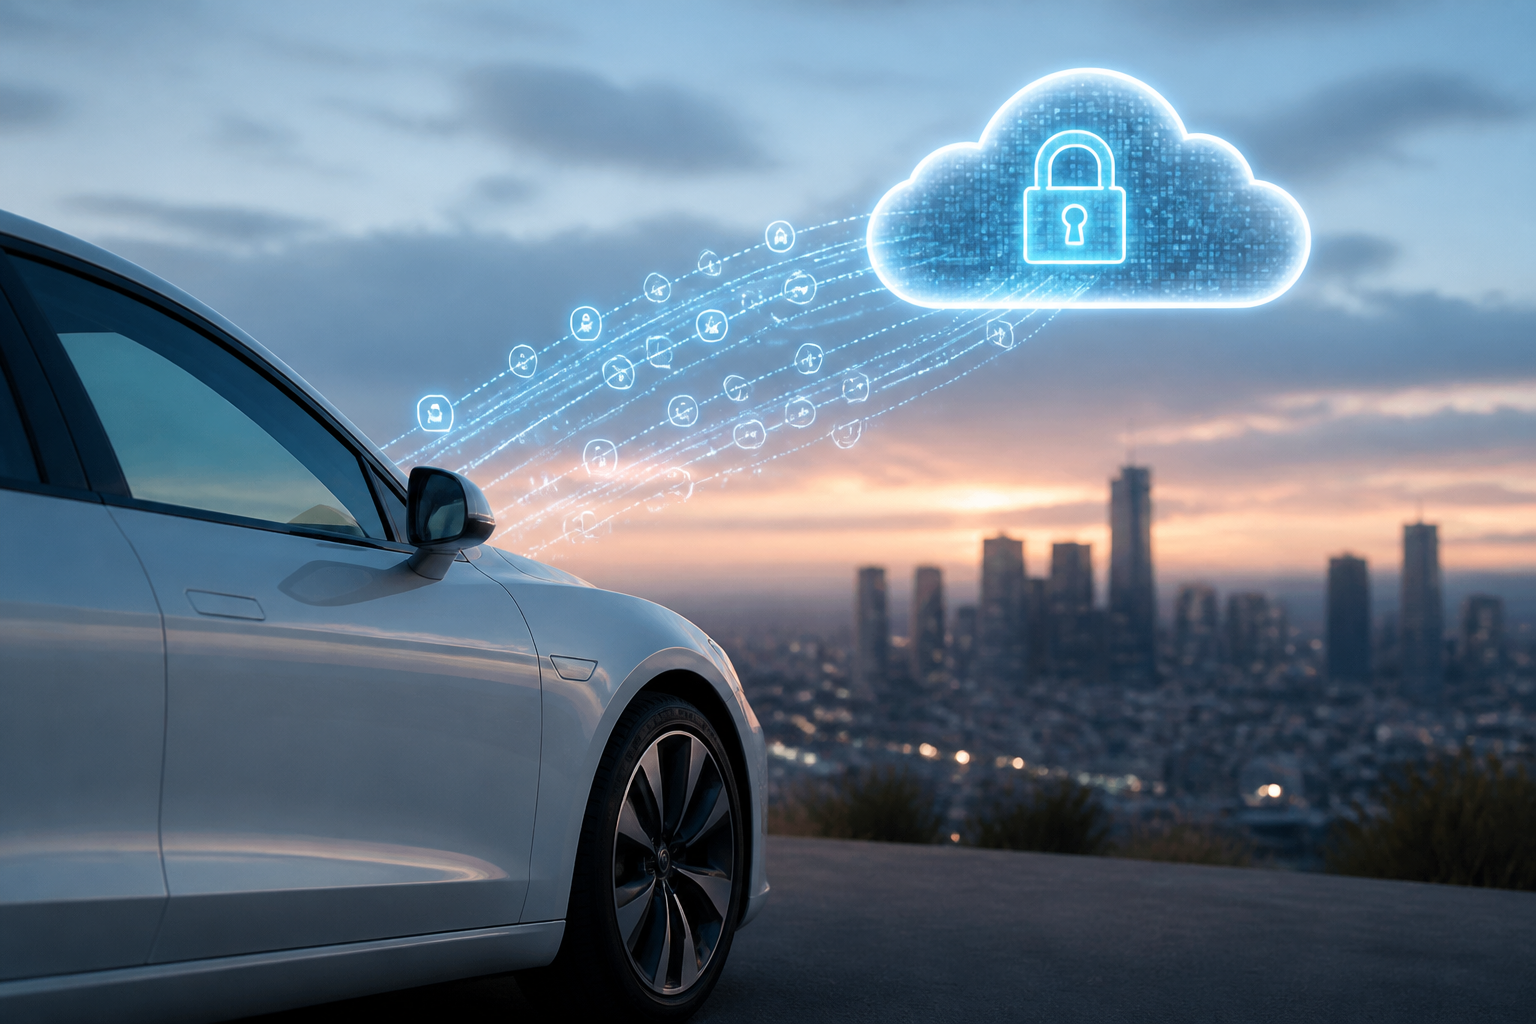
The integration of advanced technology in electric vehicles (EVs) has brought unprecedented levels of connectivity and data generation. From driving habits to battery health, your EV is a sophisticated data hub. For the insurance industry, this data offers a potential pathway to more precise risk assessment and personalized premiums. However, this convergence also raises significant questions about data privacy, ownership, and the regulatory frameworks designed to protect consumer information. As a Senior Auto Insurance Analyst at EV Insurance Hub, I've observed firsthand how the emerging landscape of data privacy laws is beginning to reshape how insurers collect, use, and share vehicle data, directly influencing underwriting models and, ultimately, your insurance costs.
The Rise of Connected EVs and Data Collection
Modern electric vehicles are essentially computers on wheels, equipped with an array of sensors, cameras, and connectivity features that generate vast amounts of data. This data isn't just for navigation or infotainment; it's a rich source of information about how the vehicle is driven, maintained, and even where it's parked. Automakers collect this data for various purposes, including improving vehicle performance, offering over-the-air updates, and providing connected services. However, the potential for this data to be shared with third parties, including insurance companies, is a growing area of focus for consumers and regulators alike.
The types of data collected can be incredibly granular, ranging from acceleration and braking patterns to precise GPS location, speed, mileage, and even seatbelt usage. For EVs specifically, data related to charging habits, battery degradation, and energy consumption also becomes relevant. This information, when aggregated and analyzed, can paint a comprehensive picture of a driver's risk profile. The sheer volume and specificity of this data far exceed what traditional insurance underwriting models have historically relied upon, such as credit scores or demographic information.
The increasing sophistication of these data collection systems means that virtually every interaction with your EV could potentially be logged. This includes diagnostic trouble codes (DTCs) that indicate potential mechanical issues, infotainment system usage, and even biometric data if advanced driver monitoring systems are in place. The challenge lies in determining who owns this data, how it can be used, and what protections are in place to prevent misuse or unauthorized access. This is particularly pertinent as more insurers explore telematics and usage-based insurance (UBI) models for EVs.
How EV Data Influences Insurance Underwriting
For insurance companies, access to real-time or historical vehicle data represents a significant opportunity to refine their underwriting processes. Traditional underwriting relies on broad actuarial tables and statistical models based on demographics, vehicle type, driving history, and claims data. Connected vehicle data, however, allows for a much more individualized assessment of risk. Insurers can potentially move beyond generalized risk pools to offer premiums that more accurately reflect an individual driver's actual behavior.
Here's how EV data can influence insurance underwriting:
- Driving Behavior Analysis: Data on acceleration, braking, cornering, and speed can indicate aggressive or cautious driving styles. Drivers exhibiting safer habits might qualify for lower premiums.
- Mileage and Usage Patterns: Lower annual mileage often correlates with lower accident risk. Data can confirm actual mileage, as well as typical routes and times of day driven, which can impact risk assessment.
- Vehicle Maintenance and Health: Diagnostic data can provide insights into the vehicle's condition, potentially flagging issues that could lead to future claims. For EVs, battery health data could become a factor, as battery replacement is a significant cost.
- Location Data: GPS data can reveal where a vehicle is typically driven and parked, correlating with crime rates or accident frequency in specific areas.
- Advanced Driver-Assistance Systems (ADAS) Usage: Data on how frequently and effectively ADAS features (like automatic emergency braking or lane-keeping assist) are used could influence perceived risk, as these systems are designed to prevent accidents.
While the promise of more precise pricing is appealing, the methodology for translating this data into premium adjustments is complex. Insurers often use proprietary algorithms to analyze telematics data, which can result in premium discounts ranging from 5% to 30% for consistently safe drivers participating in UBI programs. Conversely, data indicating high-risk behavior could theoretically lead to higher premiums or even non-renewal, though regulatory restrictions often limit the ability to penalize based solely on telematics data in some jurisdictions. The key is transparency and consumer consent, which is where data privacy regulations play a critical role.
Key Data Privacy Regulations and Their Reach
The rapid evolution of connected vehicle technology has outpaced the development of specific, comprehensive regulations for automotive data. However, existing general data privacy laws are increasingly being applied to vehicle data, creating a complex legal landscape for automakers, tech companies, and insurers. Understanding these regulations is paramount for both businesses and consumers.
- General Data Protection Regulation (GDPR) – EU: Enacted in 2018, GDPR is one of the most stringent data privacy laws globally. It applies to any organization processing the personal data of EU residents, regardless of where the organization is located. Key principles include:
- Lawfulness, Fairness, and Transparency: Data must be processed lawfully, fairly, and in a transparent manner.
- Purpose Limitation: Data must be collected for specified, explicit, and legitimate purposes and not further processed in a manner incompatible with those purposes.
- Data Minimization: Only data that is necessary for the specified purpose should be collected.
- Accuracy: Personal data must be accurate and kept up to date.
- Storage Limitation: Data should be kept no longer than necessary.
- Integrity and Confidentiality: Data must be processed in a manner that ensures appropriate security.
- Accountability: Organizations must be able to demonstrate compliance.
- California Consumer Privacy Act (CCPA) and California Privacy Rights Act (CPRA) – US: The CCPA, effective 2020, and its expansion, CPRA (effective 2023), grant California consumers significant rights regarding their personal information. While not specific to vehicle data, it broadly covers data collected by businesses, including automakers and insurers. Key rights include:
- Right to Know: Consumers can request information about the personal data collected, sold, or shared.
- Right to Delete: Consumers can request deletion of their personal data.
- Right to Opt-Out: Consumers can opt-out of the sale or sharing of their personal data.
- Right to Correct: Consumers can request correction of inaccurate personal data.
- Right to Limit Use and Disclosure of Sensitive Personal Information: This includes precise geolocation data, which is highly relevant for connected vehicles.
- Emerging Sector-Specific Guidance: Beyond general privacy laws, organizations like the National Highway Traffic Safety Administration (NHTSA) in the US and the European Commission are exploring guidelines and regulations specifically for connected vehicle data, focusing on safety, cybersecurity, and privacy. The automotive industry itself, through bodies like the Alliance for Automotive Innovation, has also developed voluntary principles for consumer privacy in connected vehicles, though these typically fall short of statutory requirements.
For connected vehicles, this means explicit consent is often required for data collection and sharing, and individuals have rights to access, rectify, or erase their data.
These laws have set a precedent, influencing other US states to enact similar privacy legislation, creating a patchwork of regulations across the country.
The challenge for insurers operating across multiple jurisdictions is to navigate these varying regulations, ensuring compliance while still leveraging the benefits of vehicle data. Non-compliance can lead to significant fines, reputational damage, and loss of consumer trust.
The Impact on Personalized Pricing and Transparency
The tension between data-driven personalized pricing and consumer privacy is at the heart of this evolving landscape. Insurers are keen to offer premiums that accurately reflect individual risk, moving away from broader classifications that might penalize safer drivers. With rich EV data, they can theoretically offer more competitive rates to those who demonstrate responsible driving habits, maintain their vehicles well, and drive less frequently in high-risk areas. This could lead to a significant shift in how premiums are calculated, potentially making insurance more equitable for many.
However, the implementation of personalized pricing models based on granular vehicle data necessitates a high degree of transparency. Drivers need to understand:
- What data is being collected: A clear, plain-language explanation of all data points gathered from their EV.
- How that data is being used: Specific examples of how driving behavior, mileage, or battery health data translates into premium adjustments.
- Who the data is shared with: Disclosure of any third parties (e.g., data brokers, telematics providers, repair shops) receiving their vehicle data.
- How to access and control their data: Clear mechanisms for drivers to review their data, correct inaccuracies, or opt-out of certain data-sharing practices.
Without this transparency, personalized pricing can feel opaque and unfair, leading to consumer distrust. Regulatory bodies are increasingly scrutinizing these practices. For instance, some states in the US require insurers to disclose how telematics data is used and provide options for consumers to opt-out. In the EU, GDPR's emphasis on explicit consent means that insurers must obtain clear permission before using vehicle data for underwriting purposes, and this consent must be easily withdrawn.
The goal is to strike a balance: enabling insurers to innovate and offer more tailored products, while simultaneously empowering drivers with control over their personal information. This balance is crucial for the long-term adoption of telematics and data-driven insurance models within the EV market.
Challenges and Opportunities for Insurers and Drivers
The intersection of EV data, privacy regulations, and insurance presents both significant challenges and compelling opportunities for all stakeholders.
Challenges for Insurers:
- Regulatory Compliance: Navigating the complex and evolving patchwork of privacy laws across different regions (US states, EU member states, etc.) is a monumental task. Ensuring consistent compliance while leveraging data requires robust legal and technical frameworks.
- Data Ingestion and Analysis: The sheer volume and variety of data from connected EVs require advanced analytics capabilities, including AI and machine learning, to extract meaningful insights for underwriting.
- Consumer Trust and Acceptance: Overcoming consumer skepticism about data sharing and demonstrating the clear benefits of UBI programs is crucial for widespread adoption. A lack of trust can severely limit data access.
- Data Security: Protecting sensitive vehicle and personal data from cyber threats, breaches, and misuse is paramount. A single breach could have severe financial and reputational consequences.
- Standardization: Lack of standardized data formats and APIs across different EV manufacturers complicates data integration for insurers.
Opportunities for Insurers:
- More Accurate Risk Assessment: The ability to price policies more precisely based on individual behavior can lead to fairer premiums and reduced losses from mispriced risks.
- Enhanced Customer Engagement: Telematics programs can offer real-time feedback to drivers, encouraging safer habits and fostering a more proactive relationship between insurer and policyholder.
- New Product Development: Data insights can lead to innovative insurance products, such as dynamic pricing, on-demand coverage, or tailored services for EV owners (e.g., battery health monitoring).
- Fraud Detection: Detailed vehicle data can assist in identifying fraudulent claims by providing verifiable information about accident circumstances.
- Competitive Advantage: Insurers who effectively leverage data while maintaining strong privacy practices can gain a significant competitive edge in the rapidly growing EV market.
Challenges for Drivers:
- Privacy Concerns: The fundamental worry about who has access to their driving data and how it might be used against them (e.g., for marketing, surveillance, or discriminatory pricing).
- Understanding Complex Policies: Deciphering the terms and conditions related to data sharing in insurance policies and vehicle manufacturer agreements can be overwhelming.
- Potential for Higher Premiums: While safe drivers may benefit, those whose data reveals higher-risk behavior could face increased costs, even if their traditional record is clean.
- Data Insecurity: The risk of personal and vehicle data being compromised in a cyberattack.
Opportunities for Drivers:
- Potentially Lower Premiums: Safe and responsible EV drivers can qualify for significant discounts, often ranging from 5% to 25%, by opting into telematics programs.
- Fairer Pricing: Premiums that better reflect individual risk rather than broad demographic averages.
- Improved Driving Habits: Real-time feedback from telematics devices can help drivers identify and correct unsafe behaviors, leading to fewer accidents.
- Faster Claims Processing: In some cases, vehicle data can expedite claims by providing clear evidence of accident circumstances.
- Enhanced Vehicle Safety and Maintenance: Data-driven insights can alert drivers to potential vehicle issues or recall needs, improving safety and extending vehicle life.
The industry is still in the early stages of fully integrating EV data with insurance. The path forward will require continuous dialogue between regulators, automakers, insurers, and consumers to build a system that is both innovative and trustworthy.
Navigating Your Data Rights and Future Outlook
As an EV owner, understanding and actively managing your data rights is becoming as important as understanding your vehicle's features. While the specifics vary by region, general principles empower you to have a say in how your vehicle data is used. Here are steps you can take:
- Read Vehicle Manufacturer's Privacy Policies: Before purchasing an EV, and periodically thereafter, review the privacy policy of the vehicle manufacturer. This document outlines what data is collected, how it's used, and with whom it might be shared.
- Review Insurance Policy Terms: If you opt into a telematics or usage-based insurance program, carefully read the terms and conditions related to data collection, usage, and sharing. Understand how your data will impact your premiums.
- Utilize In-Vehicle Privacy Settings: Many modern EVs offer in-vehicle settings to manage data collection, location tracking, and connectivity. Explore these options and configure them according to your comfort level.
- Exercise Your Rights Under Privacy Laws: If you reside in a jurisdiction with strong data privacy laws (like California or the EU), be aware of your rights to access, correct, delete, or opt-out of the sale/sharing of your personal data. Contact the relevant company's privacy officer if you wish to exercise these rights.
- Ask Questions: Don't hesitate to ask your EV dealer, manufacturer, or insurance provider specific questions about their data practices. Demand clear and understandable answers.
The future of EV insurance will undoubtedly be shaped by ongoing technological advancements and evolving regulatory frameworks. We can anticipate:
- More Granular Data Collection: As vehicles become more autonomous, data collection will become even more sophisticated, potentially including driver attention levels, environmental context, and even biometric data.
- Standardized Data Sharing Protocols: Pressure from regulators and consumer groups may lead to more standardized, secure, and transparent ways for vehicle data to be shared, potentially through a neutral third-party platform rather than direct manufacturer-to-insurer links.
- Increased Focus on Cybersecurity: As vehicle data becomes more valuable, the need for robust cybersecurity measures to protect it will intensify, influencing insurance coverage for cyber risks.
- Dynamic Pricing Models: Insurers may move towards more dynamic pricing models where premiums adjust almost in real-time based on driving behavior, road conditions, or even vehicle occupancy.
- New Insurance Products: Expect the emergence of specialized insurance products tailored to specific EV data points, such as policies that adjust based on battery health or charging habits.
Ultimately, the goal for both consumers and the industry should be a system where data is used responsibly to create safer roads and fairer insurance pricing, all while upholding individual privacy rights. Staying informed and proactive will be key for EV owners in this evolving landscape.
Key takeaways
- Modern EVs collect extensive data on driving behavior, vehicle health, and location, which is highly valuable to insurance underwriters.
- Data privacy laws like GDPR and CCPA are increasingly applied to vehicle data, mandating transparency, consent, and consumer control over how their information is used.
- EV data enables more personalized insurance pricing, potentially offering discounts for safe drivers, but requires clear communication on how data influences premiums.
- Insurers face challenges in regulatory compliance and data security, while drivers must actively manage their data rights to ensure privacy and fair pricing.
- The future will see more granular data, standardized sharing protocols, and dynamic insurance products, making informed consumer engagement essential.
Frequently asked questions
Q.What kind of data does my EV collect that could impact insurance?
Your EV can collect data on driving behavior (speed, acceleration, braking), mileage, location, time of day driven, battery health, charging habits, and even ADAS feature usage. This granular information helps insurers assess individual risk more accurately than traditional methods.
Q.How do data privacy laws like GDPR and CCPA affect EV insurance?
These laws grant consumers rights over their personal data, including vehicle data. They require companies, including insurers, to be transparent about data collection and usage, obtain consent, and provide options for consumers to access, correct, or opt-out of data sharing, influencing how personalized premiums are set.
Q.Can my EV data increase my insurance premiums?
While telematics programs often offer discounts for safe driving, data indicating high-risk behaviors (e.g., frequent hard braking, excessive speeding) could theoretically lead to higher premiums or make you ineligible for discounts. However, regulations in some areas limit the ability to penalize solely based on telematics data without clear consent and transparency.
Q.Do I have control over what EV data is shared with my insurer?
Yes, to a significant extent. Most telematics programs are opt-in, requiring your explicit consent. Additionally, privacy laws like CCPA and GDPR give you rights to know what data is collected, how it's used, and often to opt-out of its sale or sharing. Your EV itself may also have in-vehicle privacy settings.
Q.What are the benefits of sharing my EV data with insurers?
The primary benefit is the potential for personalized, lower insurance premiums if your driving habits are safe. Many drivers participating in usage-based insurance programs report discounts ranging from 5% to 25%. It can also lead to fairer pricing based on actual risk, rather than broad demographic averages.
References
Market analyst with 22+ years tracking P&C insurance regulation, M&A and emerging-risk trends.
Continue reading
How Extreme Temperatures Affect Your EV Insurance Premiums & Claims
This article will analyze how living in regions prone to extreme heat or cold, or experiencing sudden climate events, can influence EV insurance premiums, repair costs, and claim frequency. We'll use data from regions with significant temperature variations to illustrate the underwriting implications. Use this checklist to compare premiums, deductibles, repair support, and policy wording before renewal.
Beyond Charging: How EV Grid Integration Impacts Your Insurance Premiums
As Vehicle-to-Grid (V2G) and Vehicle-to-Home (V2H) technologies become more prevalent, this article will analyze how an EV's role as a mobile energy storage unit could reshape insurance risk profiles, underwriting practices, and ultimately, premiums, exploring potential liabilities and new coverage needs arising from direct interaction with the electrical grid. Use this checklist to compare premiums, deductibles, repair support, and policy wording before renewal.
How EV Data Privacy Laws Shape Your Insurance Premiums & Underwriting
As connected vehicles collect vast amounts of driver data, this article will explore the evolving landscape of data privacy regulations (like GDPR, CCPA, and emerging state laws) and their direct impact on how EV insurers underwrite policies, set premiums, and handle claims, particularly for telematics data. It will analyze the balance between personalized rates and consumer privacy rights. Use this checklist to compare premiums, deductibles, repair support, and policy wording before renewal.